Overview:
- Ridge Street qualifies a long-term rental on one to four units at a 1.0 DSCR (debt service coverage ratio), a 660 credit score, and 20% down. On short-term rentals it asks for a 700 score and prior ownership experience, and on five- to ten-unit multifamily for a 1.15 ratio and 25% down.
- Lenders take the rental income figure from the appraisal, not the borrower. On a vacant purchase they use the appraiser's market rent, and on a cash-out refinance they use the rent in place. Ridge Street counts 80% of an AirDNA short-term rental projection, not the full estimate.
- Ridge Street underwrites the condition of the property, not just the borrower. It has to be ready to rent at closing, so an appraiser who flags deferred maintenance can delay the loan until the work is done.
A DSCR loan is a type of investment property financing that qualifies real estate investors based on a property’s rental income rather than personal income verification.
The debt service coverage ratio (DSCR) is used to measure whether that income is sufficient to cover monthly mortgage payments, property taxes, insurance, and any association dues.
There is no universal DSCR loan requirement. Each lender sets its own minimum ratio, credit floor, leverage cap, and reserves rule based on its capital source and risk tolerance.
The requirements also depend on the type of deal. A single-family long-term rental is not reviewed the same way as a short-term rental or a five- to ten-unit building. As risk increases, credit standards can rise, leverage caps can come down, and the investor’s experience matters more.
This guide explains how DSCR loan requirements work, how lenders calculate the ratio, and what investors need to prepare before applying. It also covers the document checklist, state-specific rules, and the steps to qualify.
What Are The Requirements For A DSCR Loan?
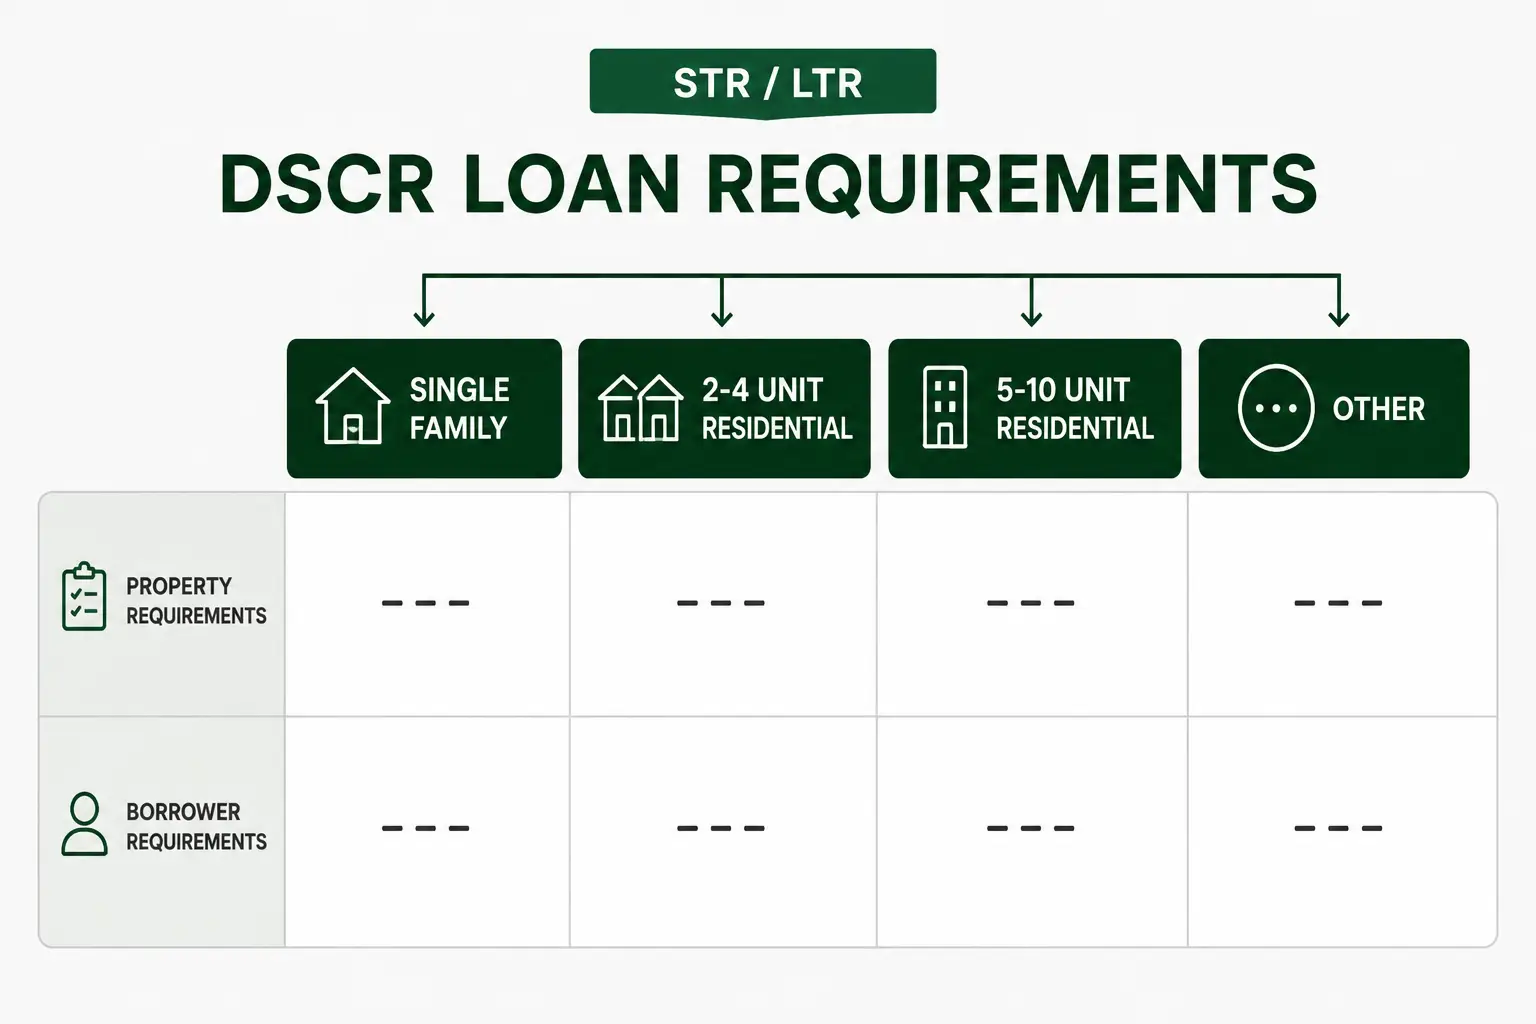
Lenders assess DSCR loans using measurable criteria tied to the property’s income and overall risk profile. The requirements for a DSCR loan vary depending on the investment strategy (Long Term Rental vs. Short Term Rental) and by the property type (Single Family, 2-4 Unit Residential, and 5-10 Unit Residential).
Unlike conventional mortgages that rely on your tax returns, pay stubs, and personal income, DSCR loans are approved based primarily on the property’s cash flow. This means lenders require less borrower income documentation and focus more on whether the property can comfortably cover its own debt payments.
DSCR Loan Requirements by Property Type
The table gives the baseline thresholds. The sections below walk through each requirement and explain how Ridge Street Capital underwrites it.
Minimum DSCR Ratio Requirements
Ridge Street Capital approves one to four unit rentals at a DSCR of 1.0, and five to ten unit multifamily at 1.15. A property at exactly 1.0 earns enough rent to cover its full monthly payment and nothing beyond it. We can usually qualify the loan at that level, but the borrower should expect the highest loan rate tier because the deal carries more risk.
DSCR ratio above 1.25 changes the loan pricing. Lenders see the extra margin as a cushion, because a vacant month or a tax increase will not immediately put the loan payment at risk. In practice, an investor with a 1.35 DSCR may receive a lower rate than one at 1.05, even with the same credit score and leverage, because the extra coverage helps absorb vacancy, tax increases, or insurance changes.
Credit Score Requirements for a DSCR Loan
Ridge Street Capital sets the floor at FICO 660 for long-term rentals. Short-term rentals and five to ten unit multifamily start at 700, because projected booking revenue and multi-unit operations both carry more variability than a signed twelve-month lease on a SFM.
Above those minimums, every 20 FICO points improves the rate. Two investors buying the same property at 680 and at 760 might see different terms.
Credit history matters too. A recent bankruptcy, foreclosure, or late mortgage payment within the past four years will raise a red flag.
Check the FICO pricing tool in this Credit Score requirement guide to see which credit tier you fall into and how that tier may affect your DSCR loan rate.
Down Payment and LTV Requirements
A one to four unit property requires 20% down, which is the same thing as 80% LTV, or loan-to-value. Five to ten unit multifamily requires 25%, capping leverage at 75%.
For DSCR cash-out refinances deals, private lenders usually reduce maximum LTV by 5%.The reason is simple.
On a purchase, the investor brings new cash into the deal. On a cash-out refinance, the investor is taking equity out, so lenders keep more equity in the property to reduce risk.
On top of that, a refinance also has no purchase contract or sale price to anchor value. The appraisal carries more weight, which is another reason lenders apply a lower LTV cap.
A larger down payment buys a lower rate. Contributing 25% to 30% on a rental property purchase lowers the lender's risk, and the rate follows.
Investors pay closing costs on top of the down payment, which is where deals get tight. Take a $300,000 purchase at 20% down: the investor brings $60,000 in equity, plus origination, title, escrow, and recording fees. From there, six months of payments still need to sit in reserve once the loan closes.
Cash Reserve Requirements
Every Ridge Street Capital DSCR program requires six months of PITIA. PITIA means principal, interest, taxes, insurance, and any association dues, so the reserve figure reflects the whole monthly payment.
It’s worth mentioning that private lenders do not deduct vacancy, repairs, management, utilities, or other operating costs when they calculate DSCR. That means a property can qualify at 1.0 DSCR on the lender’s math and still lose money each month after real expenses are included. Investors should run their own cash flow analysis before making an offer, not rely only on the DSCR ratio.
Our guides on how to estimate rental property cash flow and building a rental property pro forma walk through the expense lines that sit outside the DSCR calculation.
Checking, savings, money market, and brokerage accounts can count toward reserves. Retirement accounts may count at a discount because withdrawals can create taxes or penalties.
Eligible Property Types for a DSCR Loan
The three tables below give the full underwriting standard for each property type, including the notes that apply only to that category. What stays the same across all property types is that personal income verification is not required, and reserves remain at six months of PITIA.
DSCR Loan Requirements for Long-Term Rental, 1-4 Unit Properties
Standard DSCR loan requirements for single-family homes and condos follow the same core underwriting framework across most lenders, with minor variation by property type.
DSCR Loan Requirements for Short-Term Rental, 1-4 Unit Properties
DSCR loan requirements for short- term rentals add income evaluation overlays that standard long-term rental programs do not require, since projected booking revenue carries more variability than a signed lease.
DSCR Loan Requirements for Multifamily Properties, 5-10 Unit
DSCR loan for multifamily properties introduces higher reserve and experience thresholds as unit count increases, reflecting the larger scale and operational complexity of a 5-10 unit asset.
How Lenders Calculate the DSCR Ratio
Lenders use the debt service coverage ratio (DSCR) to determine whether a property’s income is sufficient to cover its debt obligations. The ratio compares net operating income (NOI) to total debt service, which includes the monthly mortgage payment, property taxes, insurance, and HOA fees.
DSCR = Net Operating Income ÷ Total Debt Service
On purchase transactions, most properties acquired with a DSCR loan will be vacant. In this case, the rental income number used in the DSCR calculation will be the “Appraised Market Rent”. When you purchase a property with a DSCR Loan, the property will always be appraised. In the Standard Residential Appraisal Form, there will be a Market Sale Value and a Market Rental Value.
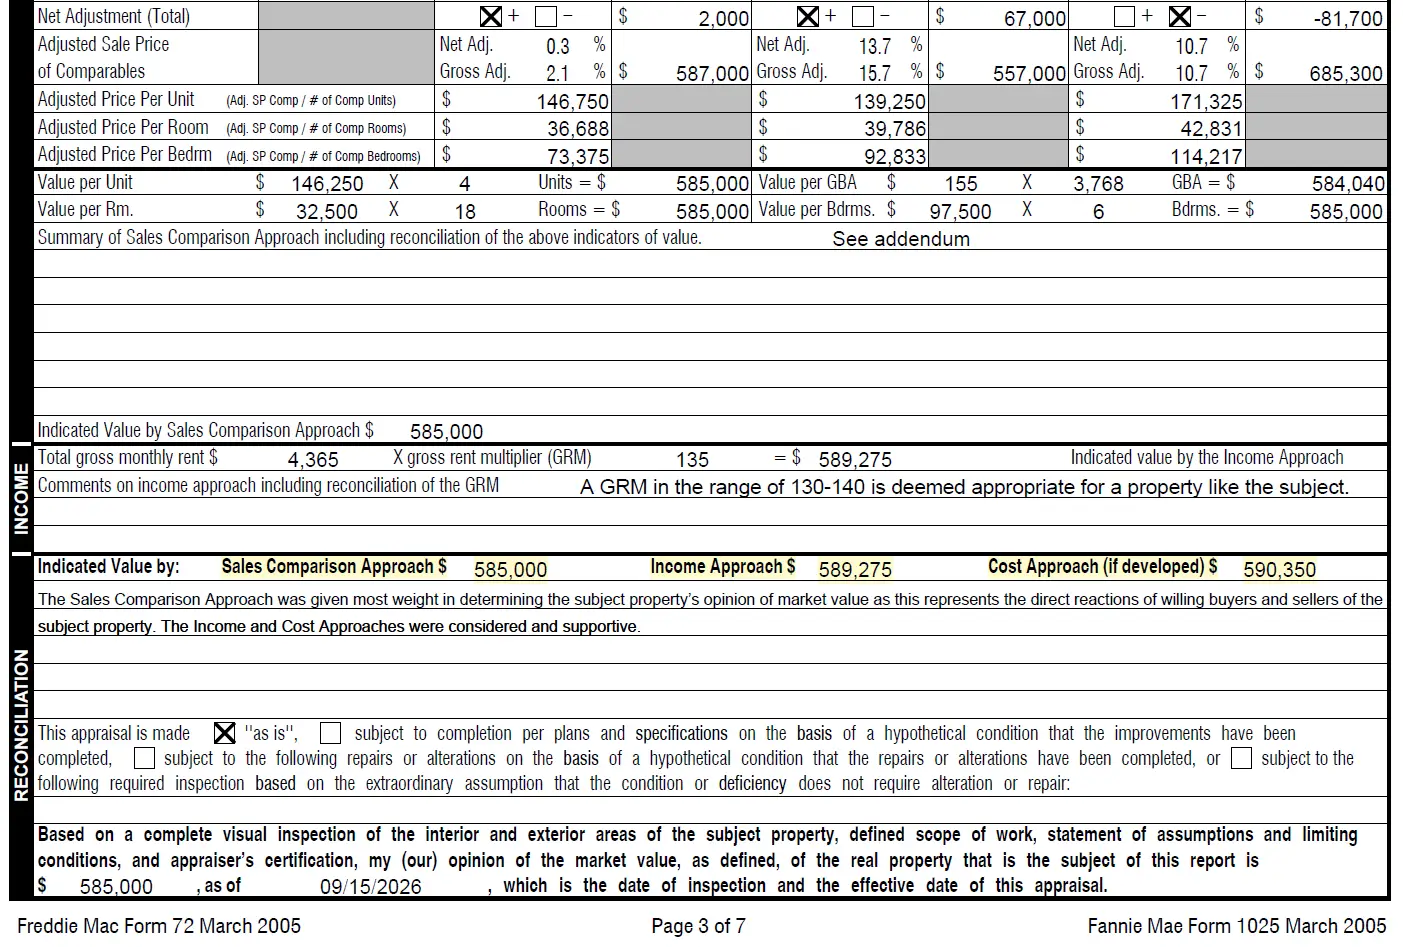
In cases where the property is being cash-out refinanced, the actual current rental value is used in the DSCR calculation.
DSCR Loan Appraisal Requirements
The appraisal on a DSCR loan does two jobs. It establishes the property value, and it establishes the rent the lender uses in the ratio. Those figures come from separate forms.
Lenders handle leased and vacant properties differently.
On a vacant property, the appraiser’s market rent is the only rent figure available, so it sets the DSCR. A signed lease changes the review. The lender compares the lease rent with the market rent on the 1007 and underwrites the lower number.
That means an above-market lease does not increase the ratio. Investors buying a property with strong in-place rents should run the DSCR on market rent before assuming the lease supports the loan.
Does the Property Need to Be Rent-Ready?
Yes, and it is an easy requirement to overlook.
A DSCR loan is underwritten on rent, so the property has to be able to produce that rent shortly after closing. Deferred maintenance is what usually gets in the way, and the appraiser is often the one who flags it.
Every appraisal includes a condition rating from C1 to C6. Fannie Mae and Freddie Mac use that scale so appraisers describe property condition consistently from one report to the next.
The appraiser assigns the rating. The lender then decides which condition ratings are acceptable for the loan.
What Repairs Can Hold Up a DSCR Loan?
An investor in Gulfport, Mississippi came to us for a DSCR cash-out refinance on a single-family rental, tenant in place at $1,195 a month, asking for $63,750. We ordered the appraisal. It came back rated C4 with a repair list attached, and the appraiser split that list in two.
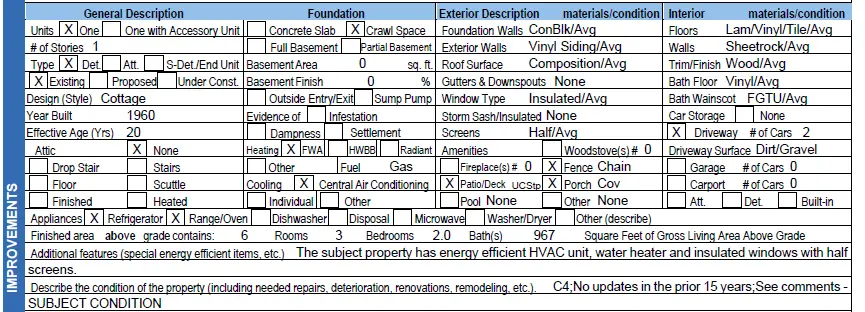
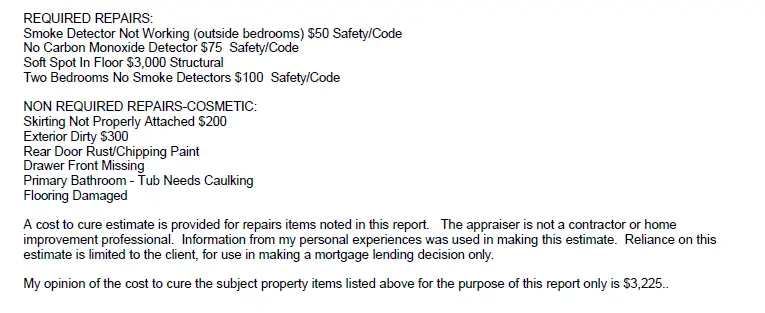
- Required before closing, $3,225 total: a non-working smoke detector outside the bedrooms, two more bedrooms with no smoke detectors, no carbon monoxide detector, and a soft spot in the floor. Three coded Safety/Code, one coded Structural.
- Not required, no effect on the loan: loose skirting, a dirty exterior, chipping paint on the rear door, a missing drawer front, caulking needed in the primary bath, damaged flooring.
How to Qualify for a DSCR Loan
Qualification starts with the property, then moves to the borrower.
The lender first confirms that the rent supports the monthly payment. After that, it checks credit score, cash to close, and reserves. Most Ridge Street DSCR files move from application to closing in 21 to 25 days.
Before you make an offer
Run the rent against the full monthly payment. A strong borrower does not rescue a property that misses the ratio, so this calculation belongs in the negotiation rather than in underwriting. Use our free DSCR calculator to check your numbers.
Before you apply
Pull your credit and confirm the cash position. The down payment, closing costs, and reserves all come out of the same account, and the reserve balance has to survive the closing.
At application
Send the property address and the purchase contract or current lease, along with borrower details. A loan officer reviews the deal and issues a term sheet.
After the term sheet
The lender orders the appraisal, which sets both the property value and the market rent used in the ratio. At Ridge Street, most DSCR loans close 21 to 25 days from application.
What Documents Are Required For A DSCR Loan?
DSCR Loans require less documentation than a standard conventional mortgage. Below we’ve created a DSCR Loan Checklist to help you make sure you have everything you need for your DSCR Loan application:
DSCR Loan Document Requirements Checklist
If you have the documentation above, you can get pre-approved for a DSCR loan with Ridge Street.
Are There Any State Level DSCR Loan Requirements?
The requirements for DSCR loans are consistent across most states. There are some minor DSCR loan requirement differences for a few states.
Pre-Payment Penalty Requirements For DSCR Loans
Most DSCR Loans have a pre-payment penalty (PPP) within the first 1-5 years.
For example, a 5YR PPP would have a declining structure of 5/4/3/2/1, where a 5% penalty would be imposed if the DSCR loan was paid off in the first year, a 4% penalty if paid off in the second year, continuing on until after the 5th year where there would be no penalty for paying off the loan early.
Some States specifically prohibit or restrict the PPP’s on DSCR loans. These states include:
In these states, the pre-payment penalty restrictions typically result in a slightly higher interest rate of +0.5% to +1.0%. Ultimately, this is not a deal-breaker for real estate investors but something to be aware of when you work with a DSCR Lender.
Flood Insurance Requirements For DSCR Loans
Most states for rental property investment don’t require rental properties to be insured with Flood Coverage. However, some coastal regions in high flood risk areas require a flood policy. Coastal regions of Florida, Texas, Alabama, Mississippi, etc, should be checked for a flood zone.
If you want to check if your property is in a flood zone, the FEMA Flood Map Service has a great free tool for checking whether or not your property is in a flood zone.
LLC Requirements For A DSCR Loan
In most states, a DSCR Loan can be closed in a borrower’s personal name or in an LLC. However, the following states specifically require that a DSCR loan be closed in an LLC:
- Georgia
- Hawaii
- Massachusetts
- New Jersey
- New York
- Pennsylvania
- Virginia
Our guide to DSCR loans for an LLC, go through the steps and process for setting up and closing a DSCR mortgage in an LLC.
Factors that Strengthen Your DSCR Loan Application
While DSCR loan requirements set the baseline for loan eligibility, certain factors can improve your DSCR loan interest rate and loan terms. Lenders reward strong financial indicators and well-performing properties because they lower overall portfolio risk.
- Higher DSCR Ratio: A DSCR above 1.20 signals that the property generates sufficient income to cover debt payments and operating expenses. These stronger DSCR ratio properties result in a lower rate.
- Strong Credit Profile: Stronger credit scores command lower interest rates. Credit scores at the bottom of the acceptable credit score range (660-680) will have the highest interest rates with scores above 760 commanding the lowest interest rates. DSCR loan interest rates improve every 20 FICO points. See an example in our guide on DSCR loan credit score requirements.
- Larger Down Payment: Investors who contribute 25–30% equity reduce the lender’s exposure and improve their loan terms. A higher down payment will command lower interest rates.
Common DSCR Loan Terms
While every lender structures investment property loans differently, most DSCR programs share similar terms and conditions. These determine how the loan performs over time and how much cash flow the property retains each month.
Get Your Deal Reviewed
Ridge Street Capital underwrites DSCR rental loans in house across 36 states. Send the property address and the current lease or purchase contract, and a loan officer runs the ratio on the actual numbers and confirms which program the deal fits. Submit through the Quick Application to receive a term sheet and pre-approval letter within 2 business hours.
Frequently Asked Questions
What minimum DSCR do lenders typically require?
Most lenders require between 1.0 and 1.25, meaning the property must generate at least enough income to cover its mortgage payments.
Can I qualify with lower credit?
Some lenders accept scores down to 620, though higher credit often improves terms. Ridge Street Capital requires a minimum credit score of 660+.
Do DSCR loans require personal income proof?
No. Approval is based on rental income and property cash flow, not tax returns or pay stubs.
Can I use a DSCR loan for short-term rentals?
Yes, specialty DSCR lenders will allow Airbnb or vacation rental income if supported by the AirDNA projected cashflow or strong short-term rental history.
Do DSCR loans require a down payment?
Yes. A one to four unit property requires 20% down and a five to ten unit property requires 25%. No DSCR program offers zero-down financing, because the secondary market investors who buy these loans require the borrower to hold equity in the deal.
Does a DSCR loan require an appraisal?
Yes, and it carries more weight than on a conventional loan. The appraisal sets both the property value and the market rent used in the DSCR calculation, so a low rent figure reduces the loan amount even when the sale price appraises cleanly.
Do DSCR loans require a credit check?
Yes. Lenders do not review tax returns or calculate debt-to-income, but they pull credit to confirm the score and the payment history. A bankruptcy, foreclosure, or late mortgage payment inside four years raises a red flag.
Zach Cohen is the Managing Partner of Ridge Street Capital, a direct private lender providing hard money and DSCR loans to real estate investors across 36 states. Under his leadership, the firm has funded nearly $100 million in investment property loans. He regularly works with real estate investors on rental property acquisitions, refinances, and fix-and-flip projects across the country.
Fix and Flip Loans
Funding For Purchase + Rehab
- $50,000 up to $3,000,000
- Interest Rate 10.5%-11.5%
- Origination Fee From 1.5%
- Up to 90% of Purchase and 100% of Rehab

DSCR Loans For Long Term Rentals
Perfect for first-time investors or experienced investors scaling their rental portfolio.
- Up to $2,000,000
- Interest Rates from 6.0%
- Origination Fee From 0%
- Up to 80% of LTV

DSCR Loans For Short Term Rentals
Designed for investors pursuing higher rents with a short term rental strategy.
- Up to $2,000,000
- Interest Rates from 6.25%
- Origination Fee From 0%
- Up to 80% LTV
Ready to Get Started?