


DSCR Loans Pennsylvania
Ridge Street Capital is a direct private lender providing financing for rental property purchases in Pennsylvania, including long-term and short-term rental loans, as well as cash-out refinancing and rate-and-term refinances.
The program works for first-time investors and for operators scaling a portfolio. Rates start at 6.0%, loans close in 21 to 25 days, and borrowers qualify using property cash flow instead of personal income.
With experience funding rentals in Philadelphia, Pittsburgh and across Pennsylvania, Ridge Street offers industry-low rates and a process that is quick, easy and reliable from application to closing.
Pennsylvania DSCR Loan Highlights
- Qualification based on rental income, not tax returns
- Minimum DSCR: 1.0
- FICO score: 660
- Loan amounts from $55,000 to $2,000,000
- Up to 80% LTV on purchase, 75% on cash-out
- Single-family, multifamily 2-10 units, condos
- Interest rates starting at 6.0%
Why Choose Ridge Street in Pennsylvania?
Over 200
Funded Loans
$90M+
Loan Volume
21-25 Days
Avg. DSCR Closing Time
In 36 States
Including Pennsylvania
Track Record
Funded DSCR Loans in Pennsylvania
Funded and sample Pennsylvania deals from Ridge Street's underwriting desk
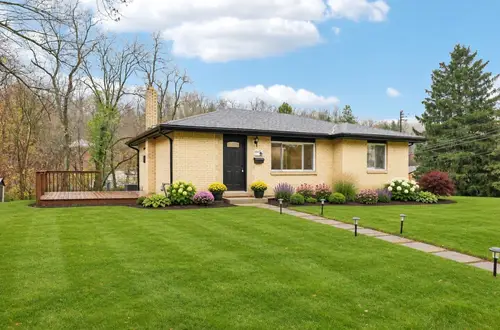
Pittsburgh, PA
Loan amount
$180,000
Rate
7.375%
LTV
75%
Type
Purchase
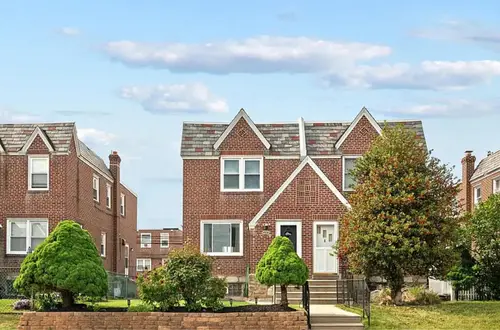
Philadelphia, PA
Loan amount
$210,000
Rate
7.5%
LTV
70%
Type
Refinance
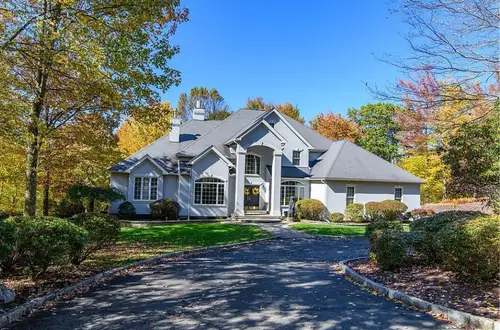
Lake Harmony, PA
Loan amount
$825,000
Rate
6.6%
LTV
75%
Type
Refinance
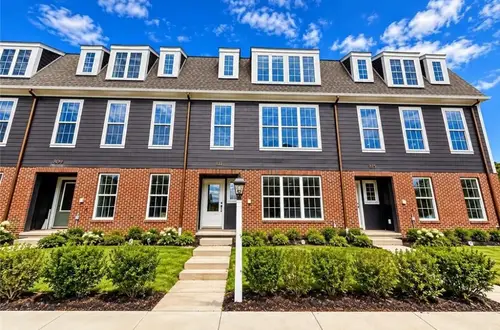
Cranberry Township, PA
Loan amount
$344,000
Rate
7.5%
LTV
80%
Type
Purchase
What Is a Pennsylvania DSCR Loan?
A Pennsylvania DSCR loan is a non-QM loan program for rental properties where qualification is based on the property's rental income, not the borrower's personal income. With DSCR loans, Ridge Street measures whether the rent covers the property's principal, interest, taxes, insurance and association fees (PITIA). DSCR loans are one of the most popular loan programs for Pennsylvania real estate investors because they are highly scalable and work well with popular investing strategies.
Pennsylvania's older cities carry some of the lowest entry prices on the east coast, and DSCR loans finance long-term holds and short-term stays in both. Approval rests on what the property earns rather than what the borrower earns, so the conventional financed-property cap falls away and an investor can hold in Philadelphia and Pittsburgh at the same time without a debt-to-income test.
However, Pennsylvania's assessment system can affect DSCR qualification more than the purchase price does. Counties assess against a base year rather than current market value, and some have not run a countywide reassessment in decades, so the assessed figure can bear almost no relation to what a property just sold for. A common level ratio is applied to bridge the gap. An investor cannot read the tax line off the purchase price here, and the number on the listing may belong to a different era entirely.
Philadelphia and Pittsburgh both carry large stocks of rowhouses converted into two and three unit rentals, and a DSCR loan for a multifamily property underwrites the combined rents across units rather than a single lease. In Philadelphia a renovated building may also carry a residential tax abatement that expires, so the ratio has to be tested against the post-abatement tax line rather than the one on today's bill.
How Pennsylvania Investors Use DSCR Loans
- Purchasing long-term rentals, including single-family homes, condos, and small multifamily properties in Philadelphia, Pittsburgh, and suburban markets across Pennsylvania.
- Financing Airbnb and vacation properties with short-term rental loans, where qualification is based on projected rental income even without booking history.
- Refinancing BRRRR projects, where investors purchase, renovate, rent, and then cash out refinance their properties when executing the BRRRR investing strategy.
- Portfolio expansion for investors scaling across multiple properties without personal debt-to-income (DTI) constraints.
When Not to Use a Pennsylvania DSCR Loan
While this loan program is well-suited for financing income-producing rental properties, there are DSCR loan pros and cons to consider, as these loans are not suitable for:
- Owner-occupied properties, including primary residences and second homes for personal use
- Properties with insufficient rental income to cover debt service
- Properties purchased for quick resale that require short-term bridge financing (Bridge-to-Sell)
- Distressed or value-add properties that are not yet rent-ready or stabilized with rental income
Benefits of Pennsylvania DSCR Loans vs. Conventional Financing
The key advantages of DSCR loans compared to conventional financing options are:
- No personal income verification
- No tax returns or W-2s
- Scalable for growing portfolios
- Less documentation than conventional loans
- Ability to close a DSCR loan in an LLC
- DSCR Loans do not report to personal credit
DSCR LOAN PRODUCTS
Pennsylvania DSCR Loans Rates & Terms
Long Term Rental
DSCR Loans Pennsylvania
Origination fee
from 0%
LTV, purchases
up to 80%
LTV, cash-out refinances
up to 75%
Loan size
$55,000 to $2,000,000
Closing
as little as 21 days
Short Term Rental
DSCR Loans Pennsylvania
Origination fee
from 0%
LTV, purchases
up to 80%
LTV, cash-out refinances
up to 75%
Loan size
$125,000 to $2,000,000
Closing
as little as 21 days
5-10 Unit Multifamily
DSCR Loans Pennsylvania
Origination fee
from 1.0%
LTV, purchases
up to 75%
LTV, cash-out refinances
up to 70%
Loan size
$350,000 to $2,500,000
Closing
as little as 30 days


DSCR LOAN CHECKLIST
DSCR Loan Pennsylvania Requirements
A complete checklist of the borrower requirements, property requirements and documents needed for a DSCR loan in Pennsylvania with Ridge Street.
Borrower Requirements
- Credit score: 660+
- No mortgage lates in the last 24 months
- Liquidity: closing costs plus 6 months PITIA
- First-time investors allowed
- Personal borrower or LLC
- US citizen or permanent resident
Property Requirements
- Property type: 1-4 unit residential or 5-10 unit residential
- DSCR of 1.0 or higher
- Property must be rent-ready
- Vacant properties permitted for both purchases and refinances
Document Checklist
- Photo ID
- Bank statement
- Entity documents (articles of formation, EIN, operating agreement) if closing in an LLC
- Appraisal, ordered by Ridge Street
- Completed loan application
How To Calculate DSCR For Pennsylvania Rental Properties
The Debt Service Coverage Ratio (DSCR) is calculated by dividing the monthly rental income of the property by the total debt service obligation.
DSCR = Rent ÷ PITIA
Where PITIA includes:
- Principal
- Interest
- Taxes
- Insurance
- HOA (if applicable)
The basis of a DSCR loan in Pennsylvania is that the rent collected from leasing the property must be greater than the total cost to own and operate it.
A DSCR of 1.0 or higher means the rental income covers all expenses and the property is considered to be cash-flowing.
Use our DSCR Loan Calculator to estimate your property's DSCR and determine whether the property qualifies for a DSCR loan.
Quick & simple
Pennsylvania DSCR Loan Process
Our DSCR Loan origination process includes 5 steps with reliable funding in 21-25 days.

Apply Or Get Pre-Approved Online
~ 2 minutes
Fill out a 2 Min Quick App with info about your project. We need some preliminary information so that we can accurately evaluate your deal and provide a quote.
If you’re looking to be pre-approved so that you can find your next deal or you’d like to get more info from one of our team members, select an option below.

Receive Your Term Sheet
~ 2 hours
Once we have your completed application, we’ll email you the Term Sheet and give you a call to provide confirmation.

Submit Docs & Order Appraisal
~ 1–7 days
Once you’ve accepted the Loan Terms, we’ll collect your remaining documents and order an appraisal. We have a low document program with no income statement documentation. See our full dscr loan requirements document checklist.

Underwriting And Final Approval
~ 2–5 days
Once you've submitted your documents and we've received the completed appraisal, the loan will enter the underwriting process. Underwriting is simply an internal review of your borrower documents and title documents before the loan is cleared to close.

Closing
~ 2 days
Once the loan is cleared to close, the title company will schedule a time for closing. Loans typically close within 48 hours of final approval.
Types of DSCR Financing Available in Pennsylvania
DSCR Purchase Loans in Pennsylvania
- An investor has found a rental and has the down payment, but can't qualify based on tax returns.
- Purchasing a rental property with ownership held through an LLC.
- Loan terms depend on DSCR, credit score and LTV.
DSCR loan guide
Rate-and-Term Refinance in Pennsylvania
- A rental property owner wants better financing terms on an existing mortgage.
- Replaces existing debt with a long-term mortgage.
- May reduce monthly payments or provide more predictable financing terms.
Refinance guide
DSCR Cash-Out Refinance in Pennsylvania
- A rental property owner has built equity and wants to fund another investment.
- Accesses equity for the next purchase, property improvements or reserves.
- Allows up to 75% LTV, subject to appraised value and existing loan payoff.
DSCR cash-out guide
DSCR Loans for Airbnb in Pennsylvania
- A buyer wants to finance a vacation rental with seasonal income and no long-term lease.
- Qualifies based on projected or actual short-term rental income.
- Must meet property eligibility, local STR regulations, and insurance requirements.
DSCR For Airbnb Guide
Pennsylvania Market Insights
Best Pennsylvania Rental Markets for DSCR Loan Investors
Pennsylvania offers rental property investors some of the deepest institutional employment markets in the Northeast, with Philadelphia anchoring the eastern corridor as the hub for pharmaceuticals, higher education, and healthcare, and Pittsburgh anchoring the western corridor as a converted steel-town-to-tech-and-medical economy. The state has no rent control and relatively landlord-friendly statutes.
Property prices and taxes vary by region, with Pittsburgh running meaningfully below Philadelphia on both. Pennsylvania consistently appears on our best states to buy rental property list, with the two markets below representing its highest-volume investor destinations.
DSCR Loans in Philadelphia
Philadelphia remains one of the most institutionally anchored rental markets in the Northeast, with employment built around the University of Pennsylvania and the Penn Medicine health system (the city's largest employer), Thomas Jefferson University and Jefferson Health, Children's Hospital of Philadelphia, Drexel University, Temple University, and a pharmaceutical cluster that includes GSK, Merck, and Spark Therapeutics.
Zillow puts the average rent near $1,750 per month in 2026, meaningfully below New York and DC. Single-family rental demand concentrates in Fishtown and Northern Liberties for younger professionals, and in Chestnut Hill and Mount Airy for family renters working in the healthcare corridor.
With one of the deepest institutional tenant bases in the US and meaningfully lower entry prices than peer Northeast metros, investors can use DSCR loans to build defensive portfolios at competitive yields.
DSCR Loans in Pittsburgh
Pittsburgh has transformed from a 20th-century steel town into one of the most consistently positioned healthcare and technology markets in the Midwest, with UPMC (the University of Pittsburgh Medical Center, the region's largest employer at over 92,000 staff), Carnegie Mellon University, the University of Pittsburgh, and a growing autonomous-vehicle and AI cluster that has drawn Google, Argo AI alumni operations, and Duolingo's global headquarters.
Zillow puts the average rent near $1,500 per month in 2026, among the most affordable for a major US metro with this employment profile. Single-family rental demand concentrates in Shadyside and Squirrel Hill for younger professionals and faculty, and in Mt. Lebanon and Upper St. Clair for family renters working in the UPMC and tech corridors.
With UPMC-and-CMU-anchored demand and very accessible pricing, investors can use DSCR loans to build portfolios in one of the most defensible mid-sized Midwest markets.
What Investors Say
From real estate investors who closed Hard Money and DSCR Loans with Ridge Street Capital across 36 states.
Pennsylvania DSCR Loan FAQ
Can I finance a 5-10 unit building in Pennsylvania with a DSCR loan?
Yes. Five- to ten-unit buildings qualify at up to 75% of the purchase price, on loans from $350,000 to $2,500,000. At Ridge Street, the program requires a DSCR of at least 1.15, a 700 credit score and prior rental ownership.
Can I get a Pennsylvania DSCR loan if I live in New York or New Jersey?
Yes. Approval is based on the Pennsylvania property's rental income, so your home state does not matter. The LLC on title must be registered in Pennsylvania.
What affects my DSCR loan rate in Pennsylvania?
Five factors set the rate on a Pennsylvania DSCR loan: the DSCR, the loan-to-value ratio, the borrower's credit score, the property type and the prepayment penalty. A higher DSCR, a larger down payment and a higher score each lower the rate. Single-family homes price lowest, followed by two- to four-unit properties.
Pennsylvania prohibits prepayment penalties on one- to two-unit loans of $329,411 or less, so a longer penalty period lowers the rate only on larger loans and on three- and four-unit properties.
Does a Pennsylvania rental have to be leased to refinance with a DSCR loan?
No. A vacant property can be refinanced once it is rent-ready. The DSCR is then based on the appraiser's market rent.
What credit score is required for a DSCR loan in Pennsylvania?
Minimums vary by lender and property type, and short-term rentals and larger multifamily buildings usually need higher scores. Ridge Street's minimum is a 660 FICO score. For an LLC, the score is taken from each member who owns 20% or more.
What is the minimum down payment on a Pennsylvania DSCR loan?
20% of the purchase price on a one- to four-unit rental, and 25% on a 5-10 unit building. On a $250,000 rowhouse, the down payment is $50,000.
Can I finance a duplex or triplex in Pennsylvania with a DSCR loan?
Yes. Two- to four-unit properties are eligible at up to 80% of the purchase price. The DSCR is calculated on the combined rent from all units, using the lower of the lease rent and the appraiser's market rent for each unit.
Do I need a rental license to own a rental property in Philadelphia?
Yes. Philadelphia requires a Rental License for the property, plus a Commercial Activity License and a city business tax account when the owner does not live there. The property must also be certified lead-safe or lead-free, and the landlord gives each tenant a Certificate of Rental Suitability.
These are city requirements for operating the rental. They are separate from loan approval.
Who pays the transfer tax on a rental purchase in Pennsylvania?
Buyer and seller are both liable, and they usually split it. The state tax is 1% of the purchase price, and the municipality and school district add a local tax, which is 1% in most places and higher in Philadelphia and Pittsburgh.
Pennsylvania has no mortgage recording tax, so the rest of a buyer's closing costs are lender and title fees.
Do DSCR loans in Pennsylvania have a prepayment penalty?
It depends on the loan size and the number of units. Pennsylvania prohibits prepayment penalties on loans of $329,411 or less (the 2026 limit) secured by one- to two-unit properties. Above that loan size, or on a three- or four-unit property of any size, you can choose a 5-year, 3-year or 1-year penalty or none, and a longer period earns a lower rate.
For DSCR refinances and cash outs, does the property have to be rented?
The short answer is no. We understand that investors who fix and refinance properties intend to refinance as soon as possible after renovating a property.This said, providing a DSCR loan on a rental property that is not rented is higher risk. We'll want to see that the market you are in is very "rentable" at the market rent for your property. We will not provide a DSCR loan on a rental property that has been listed for rent for 3 months with no bites, for example.
Do I have to close a DSCR loan in an LLC in Pennsylvania?
Yes. In Pennsylvania, Ridge Street closes DSCR loans in the name of an LLC. The LLC must be registered with the Pennsylvania Department of State and in good standing at closing. An LLC formed in another state can be used after it registers in Pennsylvania as a foreign entity.
Additional DSCR Loan Resources
Category
November 3, 2026
Learn how to finance a 1031 exchange replacement property with a DSCR loan: why it qualifies on rental income, fits the 180-day closing deadline, and closes in an LLC with no income verification required.
Category
November 3, 2026
A complete breakdown of turnkey rental properties: what the label actually means, what providers earn at each step, and the real numbers once vacancy, maintenance, and management fees are counted.
Category
November 9, 2026
Learn how lenders finance a duplex, triplex or fourplex: the 25% down payment on investment purchases, how rent from each unit counts toward qualifying, the Form 1025 appraisal, and the reserves required after closing.
Beginner & Experienced Investors
Ready to Get a Pennsylvania DSCR Loan?
Whether you have a property under contract, you're looking to be pre-approved so you can find your next deal, or you'd like to speak with an expert, Ridge Street is a leading DSCR lender in Pennsylvania and can help.