How to Refinance a Rental Property: A Full Guide for Real Estate Investors
How to refinance a rental property: steps, requirements, cash-out rules, and when the numbers actually support the decision for real estate investors.
nmin readReleased on:April 24, 2026Last updated on:October 28, 2026
Overview:
- A refinance has to recover its upfront cost. Closing costs typically run 2% to 4% of the loan amount. The refinance only makes sense if lower payments, better loan terms, or redeployed equity create enough value to offset that cost.
- Four situations usually justify refinancing. A refinance can work when it materially improves cash flow, pulls equity for a higher-return acquisition, replaces a hard money loan with long-term financing, or pays off higher-cost debt tied to the property.
- Three situations usually make refinancing the wrong move. A small rate cut may take too long to break even. A cash-out refinance with no defined use adds interest without creating return. A planned near-term sale may not leave enough time to recover the closing costs.
Most refinancing guides focus on homeowners, but refinancing a rental property involves different rules and generally stricter lending requirements. Investors also need to consider how the new loan affects cash flow and overall returns. Approaching the process like a primary residence refinance can lead to unexpected costs and financing challenges.
This guide covers the full refinancing process for rental properties: rate-and-term vs. cash-out, conventional vs. DSCR underwriting, qualification requirements, closing costs, and how to evaluate whether the numbers support the decision before applying.
Most real estate investors refinance for one of two reasons: to change the rate and loan structure, or to access equity through a cash-out refinance.
Rental Property Refinance: Rate-and-Term vs. Cash-Out
A rate-and-term refinance changes the interest rate, the loan term, or both while the balance stays the same. A cash-out refinance raises the balance and pays the difference to the investor at closing.
Rate-and-Term Refinance
A rate-and-term refinance replaces an existing mortgage with a new loan that has a different interest rate, repayment term, or both, without withdrawing equity. Investors typically use it to reduce monthly payments, switch from an adjustable to a fixed rate, or shorten the loan term.
Lenders generally apply less restrictive requirements than for cash-out refinancing, including higher LTV limits, because the borrower is not taking on additional debt to access equity.
Cash-Out Refinance
A cash-out refinance replaces the existing mortgage with a larger loan, allowing the investor to receive the difference in cash at closing. For a detailed explanation of the process and requirements, see our DSCR cash-out refinance guide.
Because the loan balance increases, lenders typically apply stricter LTV limits and higher interest rates. Ridge Street Capital allows cash-out refinancing up to 75% of the property's appraised value.
The larger loan balance also increases the amount the borrower must repay, potentially raising monthly mortgage payments. As a result, lenders must confirm that the property's rental income can support the new payment.
Why Investors Refinance a Rental Property
- Lower monthly debt service and improved cash flow.
Rental income minus expenses is the operating margin on a buy-and-hold property. A rate reduction on a $300,000 loan at 8.0% to 7.0% drops the monthly principal and interest payment from approximately $2,200 to $1,995. That's a difference of $205 per month.
- Access equity for the next acquisition.
A cash-out refinance converts built equity into capital that can be deployed as a down payment on the next property. This is the mechanism at the core of the BRRRR strategy, which stands for Buy, Rehab, Rent, Refinance, and Repeat, where the cash-out refinance funds the next acquisition rather than ending the investment cycle.
- Exit a hard money loan.
Hard money and bridge loans are short-term, typically 12 to 24 months, and are designed for acquisition and renovation, not long-term holds. Once the property is stabilized and rent-ready, refinancing a hard money loan into a 30-year fixed DSCR loan replaces the short-term debt with financing built for the hold period.
- Consolidate higher-cost debt.
Some investors carry higher-interest second liens or unsecured debt tied to the property. A cash-out refinance can retire that debt at a lower rate, reducing total monthly obligations if the equity supports it.
When a Rental Property Refinance Doesn't Make Sense
Refinancing costs money before it saves money. Closing costs on a rental property refinance typically run 2% to 4% of the loan amount. On a $300,000 loan, that is $6,000 to $12,000 paid at closing. That cost must be recovered through lower monthly payments, improved cash flow, or returns on deployed equity before the transaction becomes net positive. Until break-even is reached, the investor is often operating at a loss on the refinance.
Three conditions make refinancing the wrong move.
- First, if the rate reduction is marginal, the monthly savings are limited and the break-even period extends beyond the planned hold.
- Second, if the goal is to access equity but that capital has no defined use, taking on additional debt to hold cash or fund a lower-return use puts the investor in a worse position.
- Third, if a sale is likely in the near term, the upfront costs will not be recovered in time.
Refinancing should be driven by a specific financial outcome the numbers support, such as a rate reduction that materially improves cash flow, an equity pull that funds a higher-return acquisition, or a term change that aligns with the hold strategy. A slight investment property mortgage rate decrease is not enough. The decision should result in a clear, measurable improvement in the investor’s position.
Investment Property Refinance: Conventional vs. DSCR
Rental property refinancing is structured around two underwriting frameworks, and the differences between them often determine whether an investor qualifies.
Conventional refinancing follows Fannie Mae and Freddie Mac guidelines. Qualification is based on the borrower's personal income: W-2s, tax returns, and Schedule E rental income filings. Mortgage lenders calculate a debt-to-income ratio that includes all financed properties. This works for borrowers with strong documented income but not for self-employed investors, borrowers holding properties in LLCs, or portfolio investors approaching DTI limits.
DSCR refinancing qualifies based on the property’s rental income relative to its debt service. There is no personal income review, no DTI calculation, and no requirement for W-2s or tax returns. The property’s cash flow drives qualification. This structure is commonly used by investors holding assets in an LLC, portfolio operators, and borrowers with income that is difficult to document through traditional underwriting.
For a full comparison, see our DSCR vs. conventional loan guide.
For investors who have financed two or three properties conventionally and are approaching the point where DTI or property count limits apply, DSCR refinancing is not a backup option - it is the natural continuation of how a rental portfolio is financed at scale.
Requirements to Refinance a Rental Property
Qualification requirements differ depending on the loan type. The table below outlines the key parameters for each path.
How Much Does It Cost to Refinance a Rental Property?
Closing costs on a rental property refinance typically run 2% to 4% of the loan amount, made up of several fixed and variable line items.
Appraisal. Most rental property refinances require a full appraisal. Costs vary by property type and location, typically $500 to $900 for single-family.
Origination. Ridge Street starts at 0% origination on DSCR refinances. Conventional and broker-originated loans typically run 0.5% to 2%.
Title, escrow, and recording. Covers title insurance, escrow services, and recording the new lien. Expect $1,000 to $2,500, depending on loan size and state.
Prepaid interest and insurance. Not a fee, but a cash requirement at closing. The lender collects prepaid interest and may require an escrow cushion for taxes and insurance, which affects the cash-to-close figure.
Refinance Rental Property Case Study
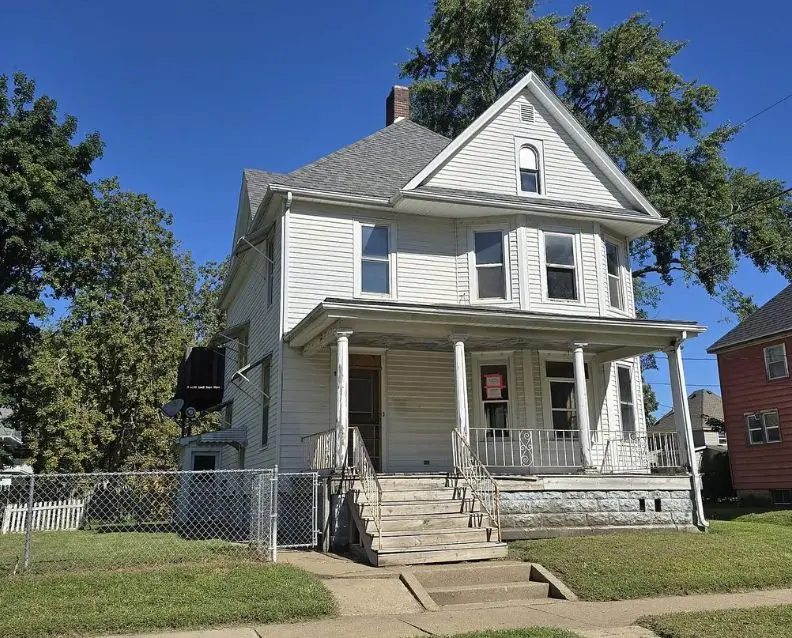
An investor in Waterloo, Iowa, held a tenant-occupied single-family rental with conventional financing. As his portfolio grew, that loan counted toward his personal debt-to-income ratio and limited what he could qualify for on future purchases. He wanted to refinance based on the property's rental income and access some of its equity in the same transaction. Ridge Street Capital structured a 30-year fixed-rate DSCR cash-out refinance, removing the mortgage payment from his personal DTI calculation.
At $82,500, the loan also fell below the minimum amount accepted by many lenders. Ridge Street offers DSCR loans under $100K, allowing investors to finance smaller rental properties based on their rental income and existing tenancy.
- Loan: $82,500, 30-year fixed at 7.625%
- LTV: 75%
- DSCR: 1.39
- Result: $6,397 in cash out
The borrower kept the property and the tenant while moving the debt off his personal balance sheet.
Read the full Waterloo, IA cash-out refinance case study.
How to Refinance a Rental Property: Step-by-step
Once the decision to refinance is made, the process follows a defined sequence. Below is a 5-step process designed to help real estate investors complete a smooth refinance.
Step 1: Run the Numbers Before Applying
Collect the current loan balance, rate, payment, and any prepayment penalty. Estimate current property value using recent closed sales, confirm the LTV fits within program limits, and run the DSCR at the projected new terms using our DSCR refinance calculator. These three checks determine whether the refinance is viable before a lender is engaged.
Step 2: Organize Documents
Document delays are the most common reason refinances miss rate-lock windows. Have the mortgage statement, insurance and tax bills, lease or rent roll, 2 months of bank statements, and LLC documents ready before applying. Conventional refinances also require 2 years of tax returns, Schedule E, and W-2s.
Step 3: Apply and Manage the Rate Lock
Once the application is submitted, the lender issues a document request list. Rate locks on investment property loans typically run 30 to 45 days. Respond to requests promptly.
Step 4: Appraisal and Underwriting
The lender orders an appraisal and verifies the application information. An appraisal below the estimated value increases LTV, which can reduce cash-out proceeds or affect eligibility. Submit complete documentation on the first underwriting response.
Step 5: Review Terms, Close, and Deploy
Before signing, review the closing disclosure against the agreed terms: interest rate, monthly payment, loan amount, closing costs, and any cash-out proceeds. If the numbers differ from the original term sheet, resolve the discrepancy before signing. After closing, verify that the prior loan is paid off, insurance and tax billing are correctly routed.
Common Mistakes When Refinancing Investment Property
- Focusing only on the interest rate. A lower rate does not automatically make refinancing worthwhile. Closing costs and a longer repayment term can offset the savings, especially if the investor plans to sell or refinance again before reaching the break-even point.
- Borrowing at the maximum LTV. Taking out the maximum available equity increases the loan balance and monthly payments, leaving less room for vacancy or unexpected expenses. Refinancing at 65% to 70% LTV can provide a stronger financial cushion and help protect cash flow.
- Applying before the property or borrower qualifies. Timing matters. Applying before the property's DSCR reaches 1.0, the borrower's credit score improves enough to qualify for better pricing, or the required seasoning period ends can lead to a decline or less favorable terms. Investors should run the numbers using our Rental Property Profit Calculator and confirm eligibility before applying.
- Choosing the wrong lender. Not every lender specializes in investment property refinancing. Lenders focused primarily on homebuyers may apply conventional underwriting requirements to rental properties, requesting unnecessary income documents or using appraisal and reserve standards that do not fit the loan program. Working with an experienced investment property lender can simplify underwriting, reduce delays, and help investors secure appropriate financing.
Why Choose Ridge Street to Refinance Your Rental Property
Ridge Street Capital works exclusively with real estate investors in 36 states. We provide refinancing for stabilized rentals, BRRRR loans, equity pulls, and transitions from hard money loans refinance into long-term financing.
To get started with rental property refinancing, investors can get pre-approved through our online application. After submission, a Ridge Street loan officer reaches out to verify property details and deal structure. The team then runs the numbers and issues a term sheet or pre-approval letter within 2 business hours.
Frequently Asked Questions
How soon can you refinance a rental property after purchase?
For a rate-and-term refinance, most DSCR lenders require 6 months of ownership. For a cash-out refinance, the standard seasoning requirement is 12 months. If the property was purchased with a fix-and-flip loan, the seasoning clock starts at the original acquisition date, not the rehab completion date.
How much equity do you need to refinance a rental property?
For a rate-and-term refinance, lenders allow up to 80% LTV, meaning 20% equity is the minimum. For a cash-out refinance, the cap is 75% LTV, requiring at least 25% equity. Properties with less equity than these thresholds will not qualify for most programs.
Can you refinance a rental property without a tenant in place?
Yes, through a DSCR lender. Conventional refinancing requires documented rental income and an active lease. DSCR lenders qualify based on projected market rent using a Form 1007 appraisal. The same applies to Airbnb loan refinancing. Ridge Street Capital uses AirDNA data to project rental income and can refinance a property without a tenant or rental history. This makes DSCR the standard approach for refinancing after renovation, before the property is leased.
Can a rental property held in an LLC be refinanced?
Yes, through a DSCR lender. Conventional loans require title to be held in the borrower's personal name. DSCR loans are structured as business-purpose loans and can be originated directly to an LLC or other entity. For investors who hold properties in an LLC for liability protection, DSCR refinancing is the natural path.
Are cash-out refinance proceeds taxable?
No. Cash-out proceeds are loan proceeds, not income, and are not taxable at closing. The interest on the new loan remains deductible against rental income, provided the proceeds are used for the investment property or another investment purpose. If proceeds are used for personal expenses, the deductibility of that portion may be limited. The specific allocation is a question for a tax advisor.
What is a reasonable break-even period for a refinance?
On a rate-and-term refinance, a break-even of 24 to 36 months is reasonable for a buy-and-hold investor with a long hold horizon. If the break-even point exceeds the expected hold period, the savings are not recovered before the property is sold or refinanced again. On a cash-out refinance, the relevant measure is the return on deployed capital against the additional monthly carrying cost from the higher balance, not the payment change alone.
What are the best places to buy rental property?
The answer depends on the investor's strategy. A cash-flow investor prioritizes states with low entry prices, landlord-favorable law, and strong rent-to-price ratios. An appreciation-focused investor weights population growth and home price momentum more heavily. Either way, state selection directly affects DSCR outcomes - insurance costs, vacancy rates, and rent trends all feed into the coverage ratio a lender calculates at underwriting. Ridge Street Capital evaluated ten states across seven criteria including gross yield, rental vacancy, rent growth, home appreciation, insurance cost, and real estate cycle position. The full ranked analysis is available in our Best States to Buy Rental Property guide.
Can investors use a mortgage to finance the replacement property in a 1031 exchange?
Yes. A loan on the replacement property is a separate transaction from the exchange funds held by the qualified intermediary, so adding leverage does not disqualify the tax deferral. Most investors use a DSCR loan for this, since it qualifies on the replacement property's rental income rather than personal income documents, which fits comfortably within the 180-day closing window. The mechanics of how financing works inside a 1031 exchange, including how the loan satisfies the IRS debt replacement requirement, depend on how the transaction is structured.
Zach Cohen is the Managing Partner of Ridge Street Capital, a direct private lender providing hard money and DSCR loans to real estate investors across 36 states. Under his leadership, the firm has funded nearly $100 million in investment property loans. He regularly works with real estate investors on rental property acquisitions, refinances, and fix-and-flip projects across the country.
Fix and Flip Loans
Funding For Purchase + Rehab
- $50,000 up to $3,000,000
- Interest Rate 10.5%-11.5%
- Origination Fee From 1.5%
- Up to 90% of Purchase and 100% of Rehab

DSCR Loans For Long Term Rentals
Perfect for first-time investors or experienced investors scaling their rental portfolio.
- Up to $2,000,000
- Interest Rates from 6.0%
- Origination Fee From 0%
- Up to 80% of LTV

DSCR Loans For Short Term Rentals
Designed for investors pursuing higher rents with a short term rental strategy.
- Up to $2,000,000
- Interest Rates from 6.25%
- Origination Fee From 0%
- Up to 80% LTV
Ready to Get Started?