


DSCR Loan Ohio
Ridge Street Capital is a direct private lender providing financing for rental property purchases in Ohio, including long-term and short-term rental loans, as well as cash-out refinancing and rate-and-term refinances.
The program works for first-time investors and for operators scaling a portfolio. Rates start at 6.0%, loans close in 21 to 25 days, and borrowers qualify using property cash flow instead of personal income.
With experience funding rentals in Cleveland, Cincinnati, Columbus, Akron and across Ohio, Ridge Street offers industry-low rates and a process that is quick, easy and reliable from application to closing.
Ohio DSCR Loan Highlights
- Qualification based on rental income, not tax returns
- Minimum DSCR: 1.0
- FICO score: 660
- Loan amounts from $55,000 to $2,000,000
- Up to 80% LTV on purchase, 75% on cash-out
- Single-family, multifamily 2-10 units, condos
- Interest rates starting at 6.0%
Why Choose Ridge Street in Ohio?
Over 200
Funded Loans
$90M+
Loan Volume
21-25 Days
Avg. DSCR Closing Time
In 36 States
Including Ohio
Track Record
Funded DSCR Loans in Ohio
Funded and sample Ohio deals from Ridge Street's underwriting desk
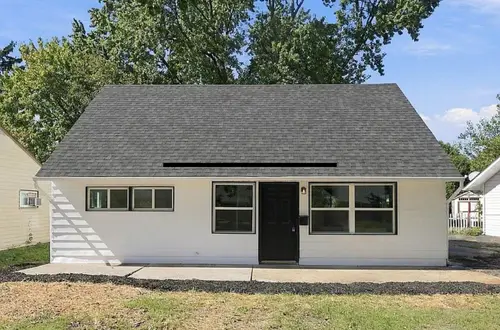
Columbus, OH
Loan amount
$140,000
Rate
7.5%
LTV
70%
Type
Refinance
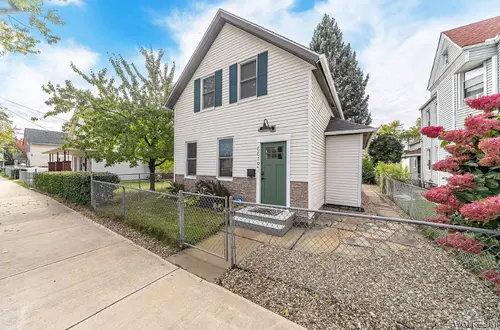
Cleveland, OH
Loan amount
$213,750
Rate
8.125%
LTV
75%
Type
Purchase
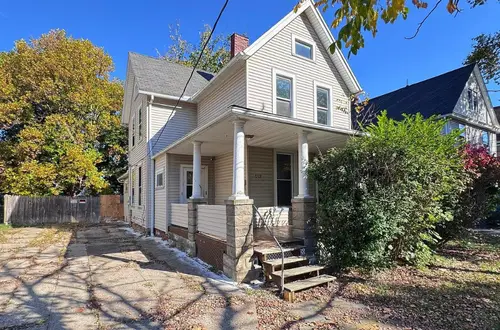
Cleveland, OH
Loan amount
$67,920
Rate
9.125%
LTV
80%
Type
Purchase
What Is an Ohio DSCR Loan?
An Ohio DSCR loan is a non-QM loan program for rental properties where qualification is based on the property's rental income, not the borrower's personal income. With DSCR loans, Ridge Street measures whether the rent covers the property's principal, interest, taxes, insurance and association fees (PITIA). DSCR loans are one of the most popular loan programs for Ohio real estate investors because they are highly scalable and work well with popular investing strategies.
Ohio offers some of the strongest rent-to-price ratios in the country and DSCR loans finance long-term holds and short-term stays in both. Qualification rests on the property's income rather than the borrower's debt-to-income ratio, so the conventional financed-property cap does not apply and an investor can accumulate doors faster here than in most states for the same capital.
However, in Ohio a below-market purchase can trigger a tax increase. School districts are permitted to file valuation complaints with the county Board of Revision, and a sale recorded well under the assessed value invites one in the opposite direction: the district argues the price proves the property is worth more than the books say. An investor who buys cheap and underwrites off the old tax line can find the ratio reset against them in the following year.
Ohio's older metros also carry an unusually large share of two and four family buildings, much of it built before 1940. A DSCR loan for a multifamily property underwrites the combined rents across units rather than a single lease, which is often what clears the ratio on a modest purchase price. The age of the stock is the trade-off: carriers and appraisers scrutinise roof, electrical and plumbing harder than they would on newer construction, and a repair escrow is frequently the difference between a file that closes and one that stalls.
How Ohio Investors Use DSCR Loans
- Purchasing long-term rentals, including single-family homes, condos, and small multifamily properties in Cleveland, Cincinnati, Columbus, Akron, and suburban markets across Ohio.
- Financing Airbnb and vacation properties with short-term rental loans, where qualification is based on projected rental income even without booking history.
- Refinancing BRRRR projects, where investors purchase, renovate, rent, and then cash out refinance their properties when executing the BRRRR investing strategy.
- Portfolio expansion for investors scaling across multiple properties without personal debt-to-income (DTI) constraints.
When Not to Use an DSCR Loan Ohio
While this loan program is well-suited for financing income-producing rental properties, there are DSCR loan pros and cons to consider, as these loans are not suitable for:
- Owner-occupied properties, including primary residences and second homes for personal use
- Properties with insufficient rental income to cover debt service
- Properties purchased for quick resale that require short-term bridge financing (Bridge-to-Sell)
- Distressed or value-add properties that are not yet rent-ready or stabilized with rental income
Benefits of Ohio DSCR Loans vs. Conventional Financing
The key advantages of DSCR loans compared to conventional financing options are:
- No personal income verification
- No tax returns or W-2s
- Scalable for growing portfolios
- Less documentation than conventional loans
- Ability to close a DSCR loan in an LLC
- DSCR Loans do not report to personal credit
DSCR LOAN PRODUCTS
Ohio DSCR Loans Rates & Terms
Long Term Rental
DSCR Loans Ohio
Origination fee
from 0%
LTV, purchases
up to 80%
LTV, cash-out refinances
up to 75%
Loan size
$55,000 to $2,000,000
Closing
as little as 21 days
Short Term Rental
DSCR Loans Ohio
Origination fee
from 0%
LTV, purchases
up to 80%
LTV, cash-out refinances
up to 75%
Loan size
$125,000 to $2,000,000
Closing
as little as 21 days
5-10 Unit Multifamily
DSCR Loans Ohio
Origination fee
from 1.0%
LTV, purchases
up to 75%
LTV, cash-out refinances
up to 70%
Loan size
$350,000 to $2,500,000
Closing
as little as 30 days


DSCR LOAN CHECKLIST
DSCR Loan Ohio Requirements
A complete checklist of the borrower requirements, property requirements and documents needed for a DSCR loan in Ohio with Ridge Street.
Borrower Requirements
- Credit score: 660+
- No mortgage lates in the last 24 months
- Liquidity: closing costs plus 6 months PITIA
- First-time investors allowed
- Personal borrower or LLC
- US citizen or permanent resident
Property Requirements
- Property type: 1-4 unit residential or 5-10 unit residential
- DSCR of 1.0 or higher
- Property must be rent-ready
- Vacant properties permitted for both purchases and refinances
Document Checklist
- Photo ID
- Bank statement
- Entity documents (articles of formation, EIN, operating agreement) if closing in an LLC
- Appraisal, ordered by Ridge Street
- Completed loan application
How To Calculate DSCR For Ohio Rental Properties
The Debt Service Coverage Ratio (DSCR) is calculated by dividing the monthly rental income of the property by the total debt service obligation.
DSCR = Rent ÷ PITIA
Where PITIA includes:
- Principal
- Interest
- Taxes
- Insurance
- HOA (if applicable)
The basis of a DSCR loan in Ohio is that the rent collected from leasing the property must be greater than the total cost to own and operate it.
A DSCR of 1.0 or higher means the rental income covers all expenses and the property is considered to be cash-flowing.
Use our DSCR Loan Calculator to estimate your property's DSCR and determine whether the property qualifies for a DSCR loan.
Quick & simple
Ohio DSCR Loan Process
Our DSCR Loan origination process includes 5 steps with reliable funding in 21-25 days.

Apply Or Get Pre-Approved Online
~ 2 minutes
Fill out a 2 Min Quick App with info about your project. We need some preliminary information so that we can accurately evaluate your deal and provide a quote.
If you’re looking to be pre-approved so that you can find your next deal or you’d like to get more info from one of our team members, select an option below.

Receive Your Term Sheet
~ 2 hours
Once we have your completed application, we’ll email you the Term Sheet and give you a call to provide confirmation.

Submit Docs & Order Appraisal
~ 1–7 days
Once you’ve accepted the Loan Terms, we’ll collect your remaining documents and order an appraisal. We have a low document program with no income statement documentation. See our full dscr loan requirements document checklist.

Underwriting And Final Approval
~ 2–5 days
Once you've submitted your documents and we've received the completed appraisal, the loan will enter the underwriting process. Underwriting is simply an internal review of your borrower documents and title documents before the loan is cleared to close.

Closing
~ 2 days
Once the loan is cleared to close, the title company will schedule a time for closing. Loans typically close within 48 hours of final approval.
Types of DSCR Financing Available in Ohio
DSCR Loans for Purchases in Ohio
- An investor has found a rental and has the down payment, but can't qualify based on tax returns.
- Purchasing a rental property with ownership held through an LLC.
- Loan terms depend on DSCR, credit score and LTV.
DSCR loan guide
Rate-and-Term Refinance in Ohio
- A rental property owner wants better financing terms on an existing mortgage.
- Replaces existing debt with a long-term mortgage.
- May reduce monthly payments or provide more predictable financing terms.
Refinance guide
DSCR Cash-Out Refinance in Ohio
- A rental property owner has built equity and wants to fund another investment.
- Accesses equity for the next purchase, property improvements or reserves.
- Allows up to 75% LTV, subject to appraised value and existing loan payoff.
DSCR cash-out guide
DSCR Loans for Airbnb Rentals in Ohio
- A buyer wants to finance a vacation rental with seasonal income and no long-term lease.
- Qualifies based on projected or actual short-term rental income.
- Must meet property eligibility, local STR regulations, and insurance requirements.
DSCR For Airbnb Guide
Ohio Market Insights
Best Ohio Rental Markets for DSCR Loan Investors
Ohio presents a diverse and robust rental property market for real estate investors, driven by its affordable housing, steady population centers, and strong demand for long-term rentals. Key cities like Columbus, Cleveland, and Cincinnati offer unique opportunities for both cash flow and appreciation.
By utilizing DSCR loans, investors can unlock financing based on rental income, making it easier to scale their portfolios. In this guide, we explore Ohio’s top rental markets and the factors that make them ideal for DSCR-funded investments. Whether you’re focusing on urban hubs or suburban growth, Ohio offers a range of opportunities to meet your investment goals.
DSCR Loans in Cleveland
Cleveland has held up as one of the Midwest's most consistent healthcare and manufacturing rental markets, with employment anchored by the Cleveland Clinic (the metro's largest employer at over 50,000 staff and ranked among the top hospital systems in the world), University Hospitals, Case Western Reserve University, Progressive Insurance, and KeyBank. Zillow puts the average rent near $1,300 per month in 2026, among the lowest for a major US metro.
Single-family rental demand concentrates in Lakewood and Rocky River for younger professionals, Shaker Heights and Cleveland Heights for family renters working in the healthcare corridor, and Ohio City and Tremont for recent downtown transplants.
With Cleveland Clinic-anchored demand and some of the lowest entry prices in any top-35 US metro, investors can use DSCR loans to build cash-flow portfolios at scale.
DSCR Loans in Cincinnati
Cincinnati has transformed from a traditional industrial economy into one of the Midwest's most diversified corporate metros, with headquarters for Procter & Gamble, Kroger, Fifth Third Bank, Macy's, Western & Southern Financial Group, and the US headquarters of GE Aviation. The University of Cincinnati and Cincinnati Children's Hospital add major institutional employment depth. Zillow puts the average rent near $1,400 per month in 2026.
Single-family rental demand concentrates in Mason, Blue Ash, and West Chester across the northern suburbs for family renters working in the P&G and Kroger corridors, and in Over-the-Rhine and Hyde Park for younger professionals. The metro's Northern Kentucky suburbs add further rental demand across the river.
With Fortune 500 corporate demand and still-accessible pricing, investors can use DSCR loans to build cash-flow portfolios anchored by one of the Midwest's deepest corporate employment bases.
DSCR Loans in Columbus
Columbus remains Ohio's fastest-growing rental market, anchored by The Ohio State University (over 61,000 students, one of the largest universities in the US), the Ohio State Wexner Medical Center, Nationwide Insurance's global headquarters, Honda's North American manufacturing headquarters in nearby Marysville, and the state government complex. The Intel semiconductor plant under construction in New Albany is adding further tech-sector employment demand.
Zillow puts the average rent near $1,500 per month in 2026. Single-family rental demand concentrates in Dublin, Westerville, and Powell for family renters working in the corporate corridor, and in the Short North and German Village for younger professionals. The metro has posted some of the strongest population growth in the Midwest since 2020.
With Fortune 500-and-Big-Ten-anchored demand and a growing tech base, investors can use DSCR loans to build portfolios in one of the Midwest's most defensible growth markets.
DSCR Loans in Akron
Akron offers investors some of the strongest rental yields in Ohio, backed by a stable institutional employment base that includes Summa Health, Cleveland Clinic Akron General, the University of Akron, and major operations for the Goodyear Tire & Rubber Company headquarters. The city's location roughly 40 miles south of Cleveland pulls commuter demand from the larger metro.
Zillow puts the average rent near $1,100 per month in 2026, among the lowest for any US city over 150,000 population. Single-family rental demand concentrates in the Highland Square and Ellet neighborhoods for family renters, and in near-university districts for student housing. The metro has posted modest population recovery in recent years after decades of decline.
With very low entry prices and institutional employers anchoring demand, investors can use DSCR loans to build cash-flow portfolios at yields larger Ohio metros cannot match.
What Investors Say
From real estate investors who closed Hard Money and DSCR Loans with Ridge Street Capital across 36 states.
Ohio DSCR Loan FAQ
Does an Ohio DSCR loan show up on my personal credit report?
No. Ridge Street does not report DSCR loans to the personal credit bureaus.
How is a DSCR loan different from a commercial mortgage in Ohio?
A DSCR loan is a 30-year loan on a residential rental with one to four units, or a small building with five to ten units, and it qualifies on the property's rent without tax returns. A traditional commercial mortgage from a bank usually requires business financials and personal income documents, and it often has a shorter term with a balloon payment.
Can I finance a duplex or fourplex in Ohio with a DSCR loan?
Yes. Two- to four-unit properties are eligible at up to 80% of the purchase price. The DSCR is calculated on the combined rent from all units, using the lower of the lease rent and the appraiser's market rent for each unit.
Can out-of-state investors get a DSCR loan in Ohio?
Yes. A DSCR loan qualifies on the property's rental income, so the borrower's home state does not affect approval.
Does an Ohio rental have to be leased to refinance with a DSCR loan?
No. Vacant units are allowed as long as the property is rent-ready. For a vacant unit, the DSCR uses the market rent from the investment property appraisal.
What is the minimum down payment on a DSCR loan in Ohio?
20% of the purchase price. On a $200,000 rental, that is $40,000. DSCR loans with no money down are not available.
Does my LLC have to be registered in Ohio to close a DSCR loan?
Yes. The LLC on title must be registered with the Ohio Secretary of State and in good standing at closing. An out-of-state LLC can be used after it registers in Ohio as a foreign entity.
What are the main requirements for a DSCR loan in Ohio?
Five requirements apply to a long-term rental in Ohio:
- Loan amount: $55,000 or more
- Credit score: 660 or higher
- DSCR: 1.0 or higher
- Down payment: at least 20%
- Reserves: closing costs plus six months of payments
Tax returns and W-2s are not required.
What is the typical interest rate on a DSCR loan in Ohio?
DSCR loan rates move with the market, so request a current quote for an exact figure. Where an Ohio loan falls depends on five factors: the DSCR, the loan-to-value ratio, the borrower's credit score, the property type and the prepayment penalty.
What does Cleveland require from owners of rental property?
Cleveland requires every non-owner-occupied rental to be registered with the city. Rental units built before 1978 also need a Lead Safe Certification, which lasts two years, or a 20-year exemption after lead hazards are removed.
These are city requirements for operating the rental. They are separate from loan approval, but budget for the lead inspection before buying an older property.
Do DSCR loans in Ohio have a prepayment penalty?
It depends on the loan size and the number of units. On one- to two-unit properties, Ohio prohibits prepayment penalties on loans under $116,356 (the 2026 limit). On larger loans, a penalty cannot exceed 1% of the original loan amount, and none can be charged after five years. Three- and four-unit properties fall outside these rules, so you can choose a 5-year, 3-year or 1-year penalty or none, and a longer period earns a lower rate.
Are DSCR loans only for investment properties?
Yes. If you are buying a piece of real estate which you intend to live in, then you would not qualify for a DSCR loan.
Additional DSCR Loan Resources
Category
September 9, 2026
Full review of pre-payment penalty options for DSCR loans.
Category
November 3, 2026
This guide on DSCR loans for multifamily properties goes over the details of 5+ Unit multifamily property financing
Category
November 3, 2026
Learn how to refinance a rental property: rate-and-term vs. cash-out, DSCR vs. conventional, costs, and the step-by-step process for real estate investors.
Beginner & Experienced Investors
Ready to Get an Ohio DSCR Loan?
Whether you have a property under contract, you're looking to be pre-approved so you can find your next deal, or you'd like to speak with an expert, Ridge Street is a leading DSCR lender in Ohio and can help.