Current Investment Property Mortgage Rates: How Pricing Works
How lenders price investment property mortgage rates by loan type, what sets the spread above Treasury yields, and what investors can do to improve a quote.
nmin readReleased on:May 18, 2026Last updated on:November 6, 2026
Overview:
- Every investment property rate has two parts: a base rate tied to Treasury yields and a credit spread added for loan-specific risk. Since the base rate moves across the market, investors are really comparing the spread when they compare lender quotes.
- The loan product sets the pricing range first. Conventional investment loans usually price lowest for borrowers who qualify on personal income. DSCR loans price higher because they qualify the property instead of the borrower’s income. Hard money loans price higher than both because the term is short, the collateral is often distressed, and the lender is taking renovation and execution risk.
Current investment property mortgage rates in November 2026 generally sit in the low-to-mid 7% range, depending on the loan type. Conventional mortgages typically fall toward the lower end, while DSCR loans sit closer to the middle of that range.
Many investors approach financing the same way they approach buying a home: searching for the lowest advertised rate and treating the lender's quote as a starting point for negotiation. However, the loan program an investor qualifies for largely determines the available pricing range. Our guide to investment property loans explains how each program works, its qualification requirements, and associated costs.
Within each program, lenders determine the final interest rate based on several factors, including the property's characteristics, loan-to-value ratio, and borrower's credit profile. Understanding how these factors affect pricing helps investors compare lenders, choose suitable financing, and make better decisions about when to lock in a rate.
In this guide, we explain how investment property mortgage rates are determined, why they differ across loan types and borrower profiles, and what investors can do to negotiate better terms.
Investment Property Mortgage Rates: Updated Live
The chart below pulls real-time data from U.S. Treasury yields and current lender pricing. It tracks the 2-year Treasury yields alongside DSCR loan rates and conventional investment property loan rates.
As of November 6, 2026, investment property mortgage rates sit slightly lower than a month ago, after the Federal Reserve held its benchmark rate at 3.75% to 4% on October 28.
Treasury yields, which set the base rate for every investor loan, have eased from their early-October highs: the 2-Year now trades near 4.5-4.6% and the 10-Year near 4.8-4.9%, down roughly 25 and 40 basis points respectively. Because conventional 30-year investor loans track the 10-Year while DSCR loans track the 2-Year, both have come off their peak.
Ridge Street Capital currently prices DSCR rental loans at 7.1-7.3%, against a market average near 7.2-7.5% across DSCR lenders, while conventional investment rates run near 7.0-7.2%. The path from here depends on December: markets price roughly an 85% chance of another Fed hike on December 9, with inflation still near 3.7%, so the recent relief may prove temporary.
Hard money and fix-and-flip loans are priced separately, typically ranging from 10% to 13%, reflecting their shorter repayment terms and the additional risks associated with renovation projects.
Investment Property Interest Rates by Loan Type
Investment property financing is not one product. Rates vary significantly based on the loan type, how the lender qualifies the borrower, and how the loan is structured. The table below reflects current market pricing across the main investor loan categories.
Rates move daily and will shift with Treasury yields and secondary market demand. The ranges above reflect current market conditions.
Rental property loans (DSCR) qualify borrowers based on the property's rental income rather than their personal income. Lenders evaluate whether the monthly rent covers the mortgage payment, without requiring W-2s, tax returns, or personal debt-to-income calculations.
These loans are used to finance long-term rentals, short-term rentals, and properties held in an LLC. Interest rates are generally 0.25-1.0% higher than conventional investment mortgages.
The reason behind that is that, unlike conventional mortgages, DSCR loans cannot be sold to Fannie Mae or Freddie Mac. Instead, lenders rely on private capital markets, where investors demand higher returns to compensate for the additional risk. This results in higher borrowing costs.
Conventional investment mortgages follow Fannie Mae and Freddie Mac guidelines. Conventional lenders evaluate the borrower's personal income, tax returns, and existing debt obligations. These loans typically offer the lowest interest rates for qualified investors, but they come with stricter down payment requirements. Also, a borrower needs to hold the investment property in their personal name (not an LLC or other entity).
Fannie Mae also limits eligible borrowers to 10 financed properties. Conventional financing can be a cost-effective option for an investor's first few rentals. But as the portfolio grows, debt-to-income requirements and property count limits can make additional financing more difficult.
Hard money and bridge loans provide short-term financing for property acquisitions and renovation projects. Hard money lenders focus primarily on the property's current value or after-repair value (ARV), allowing investors to qualify without relying heavily on personal income.
Interest rates typically range from 10% to 13%, with interest-only payments and loan terms of 6 to 18 months. Investors generally repay these loans by selling the property or refinancing the hard money loan once the project is complete.
Government-backed loans, including FHA, VA, and USDA, require owner occupancy and cannot be used to purchase a property exclusively for investment purposes. However, eligible borrowers can use FHA or VA financing to purchase a two- to four-unit property, live in one unit, and rent out the others.
This strategy, known as house hacking, allows investors to generate rental income while meeting occupancy requirements. Outside eligible owner-occupied arrangements, these government-backed programs are not available for investment property purchases.
How Are Investment Property Mortgage Rates Set?
Every investment property mortgage rate is built from two components: a base rate indexed to U.S. Treasury yields, and a credit spread the lender adds on top to compensate for the specific risks of the loan.
Let’s explore how these components work and what influences them. A better understanding can help investors compare financing options and negotiate better terms with lenders.
What Sets the Base Rate: Treasury Yields
Current investment property mortgage rates are indexed to U.S. Treasury yields, specifically the 2-year, 5-year, and 10-year Treasury yields, depending on the loan term and structure.
The Treasury yield represents what the U.S. government pays to borrow money for a given duration. Because U.S. government debt carries no default risk, it functions as the floor for all other interest rates in the economy. Every lender prices above it.
For a 30-year fixed investment property loan, the relevant benchmark is the 10-year Treasury yield. Although the loan carries a 30-year term, most investment loans are repaid within 7–10 years through refinance or sale.
The 10-year Treasury duration aligns with that expected repayment horizon, which is why lenders index long-term investment loans to it. When the 10-year Treasury yield rises, investment property mortgage rates rise with it. When it falls, rates follow.
This relationship also explains why Federal Reserve rate cuts do not automatically lower mortgage rates. The Fed controls the federal funds rate, which is what banks charge each other for overnight lending.
Mortgage rates are indexed to Treasury yields, which are priced by the bond market based on inflation expectations, economic conditions, and investor demand for long-duration assets. The two rates can move in different directions simultaneously.
The credit spread: what lenders add above the base rate
On top of the Treasury yield, every lender adds a credit spread. Ultimately, it’s the premium charged to compensate for the risks specific to the loan. This is where property characteristics, loan structure, and borrower profile all have a direct effect on pricing.
The credit spread on an investment property loan reflects:
● Occupancy type: Non-owner-occupied properties carry higher default risk than primary residences, and lenders price that into every investment loan from origination. The premium for non-owner occupancy typically adds 0.5%–1.5% above equivalent primary residence rates.
● Loan program: Conventional investment loans are sold into the Fannie Mae and Freddie Mac secondary market. DSCR and portfolio loans are sold into the non-QM secondary market. The yield requirements are higher in this market, and this is reflected in their rates.
● Borrower and deal profile: Credit score, LTV, and property type all move the spread within any given program.
● Prepayment structure: When a loan carries no prepayment penalty, the borrower can refinance as soon as rates fall, removing future income from the lender's expected return. Find more information on prepayment penalties for rental loans in our guide.
Investment Property Rates Formula:
Investment Property Mortgage Rate = Treasury Yield + Credit Spread
Here is what that looks like as a worked illustration on a rental property loan:
Reducing the loan-to-value ratio (LTV) can lower the lender's risk adjustment, while improving the credit score can lead to better pricing, typically in 20-point tiers. Lenders evaluate these factors separately, so improving either one can help borrowers secure a lower interest rate.
Why Investment Property Interest Rates Are Higher Than Primary Residence Rates?
Lenders price investment property loans above primary residence rates for two structural reasons.
- The first is borrower behavior under financial stress.
When a borrower can no longer service all of their debt obligations, the primary residence mortgage is often the last one to be missed.
The income-producing property comes after. Lenders account for that priority in the rate. That’s why investment property loans carry a premium above primary residence mortgages regardless of the borrower's credit quality.
- The next is the secondary market structure.
Primary residence mortgages are pooled and sold as mortgage-backed securities through Fannie Mae and Freddie Mac. This process is called securitization.
This government-sponsored secondary market creates deep institutional demand for conforming loans, which allows lenders to offer tighter spreads. Investment property loans are securitized through the non-QM secondary market, where institutional buyers demand higher yields to compensate for the absence of government backing. That yield requirement flows directly into the rate the borrower receives.
Multifamily Property Loans
Multifamily mortgage rates depend partly on the number of units in the property.
Lenders classify properties with one to four units as residential, so they qualify for conventional and DSCR loan multifamily programs similar to those available for single-family rentals. At the same LTV, rates are often within 0.125 to 0.25 percentage points of single-family loan pricing.
Starting at five units, properties fall under commercial multifamily financing. Lenders evaluate net operating income (NOI), which accounts for operating expenses, rather than relying primarily on gross rental income. Mortgage rates for these properties typically run 0.25 to 0.75 percentage points higher than comparable one- to four-unit financing.
There are several reasons for this difference. First, appraisals for buildings with five or more units are more complex, often requiring additional time and expense. Lenders also evaluate vacancy risk and operating performance more closely. For example, if one unit sits vacant in a five-unit building with equal rents, the property loses 20% of its potential rental income.
Ridge Street Capital finances both residential investment properties with one to four units and small multifamily buildings with five to ten units.
What Drives Investment Property Mortgage Rates on a Specific Deal
Within each investment loan program, lenders adjust interest rates based on the borrower’s qualifications, property characteristics, and transaction details. Let’s look at the 4 main factors that impact the pricing.
Credit score. Most DSCR programs require a minimum credit score of 660. Lenders typically adjust pricing in 20-point FICO tiers, with the best rates often available at 760 or higher. For example, the rate difference between a 680 and 740 credit score can range from 0.25 to 0.50 percentage points.
Loan-to-value ratio (LTV). Lenders price loans in LTV tiers, with notable rate improvements at 80%, 75%, and 70%. A borrower financing 75% of the property value will generally receive a better rate than one borrowing 80%.
Property type. Rental loans for single-family homes generally offer the most competitive rates, while condos or short-term rentals. Airbnb loans may also have higher rates when lenders use projected income from AirDNA instead of an existing lease, since future occupancy and rental income are less predictable.
Transaction type. Purchases and rate-and-term refinances typically have better pricing than cash-out refinances. When investors withdraw equity, lenders account for the additional risk through higher rates or other pricing adjustments.
How to Get the Best Mortgage Rates for Investment Property
To get a better rate on an investment property loan, start with the factors lenders use to determine pricing. Each factor affects the lender's risk assessment, so improving your qualifications in these areas can help you secure a lower interest rate.
Reduce the loan-to-value ratio. Bringing 25% down instead of 20% moves the loan below a key LTV pricing threshold on most rental loans and conventional investment programs. Lower LTV means less lender exposure in a default scenario, which reduces the credit spread directly.
Strengthen the credit score before the application. On DSCR programs, every 20-point FICO improvement up to 760 produces a pricing improvement.
Buy down the interest rate with discount points. One discount point costs 1% of the loan amount at closing and can reduce the interest rate by approximately 0.33 percentage points, depending on the lender.
On a $350,000 loan, one point costs $3,500 and saves roughly $78 per month, with a break-even period of about 45 months. For investors planning to hold the property long-term, buying down the rate can reduce total borrowing costs. However, if they expect to sell or refinance within three to five years, the upfront expense may not pay off.
Real Example: Buying Down an Investment Property Mortgage Rate with Points
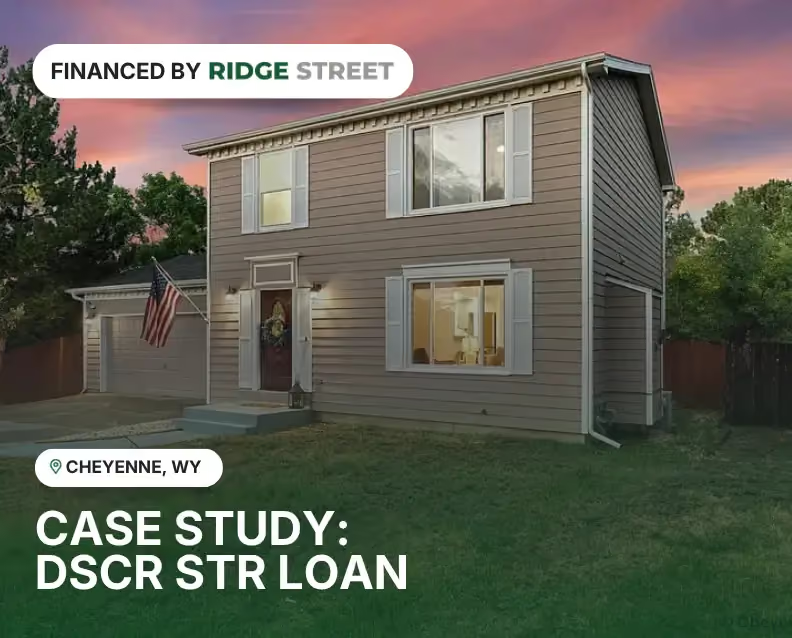
A recent Ridge Street Capital deal shows how these levers combine. An investor bought a short-term rental in Cheyenne, Wyoming, for $435,000 with a 760 FICO score, the level where pricing improvements top out, and financed at 80% LTV, the program maximum. The borrower also paid 3.5 discount points on the $348,000 loan to lock a 6.075% rate on a 30-year 5/6 ARM.
That rate stayed in place while market DSCR rates moved from the high 6% range into the low 7% range, so the borrower closed roughly one percentage point below where comparable loans were pricing. See the full Cheyenne, WY DSCR case study.
- Rate: 6.075% on $348,000 at 80% LTV, with a 760 FICO and 3.5 points ($12,180)
- Monthly savings: about $212 less per month than the same loan at 7.0%, or roughly $2,540 per year
- Break-even: about 57 months ($12,180 divided by $212), inside the five-year fixed period of the ARM
Getting Pre-Approved for an Investment Property Loan
Pre-approval for an investment property loan involves evaluating both the borrower and the specific property. Since underwriting is property-specific, the interest rate and loan terms depend on the borrower's qualifications, property characteristics, and investment strategy.
Ridge Street Capital specializes in investment property financing across 36 states, offering DSCR rental loans, fix-and-flip financing, and ground-up construction loans.
To get started, investors can submit their deal through Ridge Street's online application. A loan officer reviews the property details, evaluates the proposed financing structure, and provides a term sheet or pre-approval letter within two business hours. From there, our team works directly with the borrower through underwriting and closing.
Frequently Asked Questions
Why don't Fed rate cuts always lower mortgage rates?
The Federal Reserve controls short-term interest rates, while mortgage rates are influenced by Treasury yields and the bond market. These respond to inflation expectations, economic growth, and investor demand. As a result, mortgage rates can rise even when the Fed cuts rates. For example, following three Fed rate cuts in late 2024, mortgage rates ended the year higher as inflation expectations increased.
Can investors buy down the rate on an investment property loan?
Yes. Both conventional and DSCR loans allow borrowers to purchase discount points. One point costs 1% of the loan amount and may reduce the rate by approximately 0.25 percentage points. On a $350,000 loan, that means paying $3,500 upfront to save about $58 monthly, with a break-even period of roughly 60 months. This can benefit long-term investors but may not make sense if they plan to sell or refinance within three to five years.
Are 30-year fixed rates better than ARMs for investment properties?
It depends on the investment strategy. A 30-year fixed mortgage provides predictable payments and protects against future rate increases. Adjustable-rate mortgages (ARMs) may start 0.25 to 0.50 percentage points lower, improving initial cash flow. Fixed rates generally suit long-term holds, while ARMs may benefit investors planning to sell or refinance before the initial fixed-rate period ends.
Is it better to wait for rates to drop before buying?
Timing mortgage rates is difficult, and lower Fed rates do not guarantee lower mortgage rates. Instead, investors should evaluate whether a property generates acceptable cash flow at current financing costs. If the investment works today, future rate reductions may create an opportunity to refinance. If rates remain unchanged, the property should still support itself under the original financing terms.
Zach Cohen is the Managing Partner of Ridge Street Capital, a direct private lender providing hard money and DSCR loans to real estate investors across 36 states. Under his leadership, the firm has funded nearly $100 million in investment property loans. He regularly works with real estate investors on rental property acquisitions, refinances, and fix-and-flip projects across the country.
Fix and Flip Loans
Funding For Purchase + Rehab
- $50,000 up to $3,000,000
- Interest Rate 10.5%-11.5%
- Origination Fee From 1.5%
- Up to 90% of Purchase and 100% of Rehab

DSCR Loans For Long Term Rentals
Perfect for first-time investors or experienced investors scaling their rental portfolio.
- Up to $2,000,000
- Interest Rates from 6.0%
- Origination Fee From 0%
- Up to 80% of LTV

DSCR Loans For Short Term Rentals
Designed for investors pursuing higher rents with a short term rental strategy.
- Up to $2,000,000
- Interest Rates from 6.25%
- Origination Fee From 0%
- Up to 80% LTV
Ready to Get Started?